Master your employer obligations in 2025

If you employ staff, here are the important dates and obligations to remember throughout the year, to set yourself up for success.

Super guarantee (SG)

  • 28 January, 28 April, 28 July, and 28 October are the quarterly due dates for making SG payments.
  • The SG rate is currently 11.5% of an employee’s ordinary time earnings. From 1 July 2025, the SG rate will increase to 12%.
  • Ensure SG for your eligible employees is paid in full, on time and to the right super fund. If you don’t, you’ll need to lodge a super guarantee charge (SGC) statement and pay the SGC to us.

Fringe benefits tax (FBT)

31 March 2025 marks the end of the 2024–25 FBT year. There are 4 key steps to nail your obligations for FBT tax time.

  1. Identify if you’ve provided a fringe benefit.
  2. Determine the taxable value to work out if you have an FBT liability.
  3. Lodge an FBT return and pay any FBT owed (if you have a liability) by 21 May 2025. If your registered tax agent lodges electronically for you, you have until 25 June 2025.
  4. Keep the right records to support your FBT position.

Pay as you go (PAYG) withholding

Tax rates may increase from 1 July 2025. Use the tax withheld calculator to calculate how much you need to withhold from your employees’ payments.

Single touch payroll (STP)

Finalize your STP data by 14 July 2025 for the 2024–25 year.

This ensures your employees have the right information they need to lodge their income tax returns.

If you have any closely held payees, you may have a later due date for those payees only. Remember to finalize all employees you’ve paid in the financial year.

You can also check out our range of resources for employers.

Remember, a registered tax agent can help you with your tax and super obligations.
Lily Zhang is the founder and principal accountant of Wiselink Accountants, a CPA-qualified accounting and tax agency based in Melbourne (Camberwell) and Brisbane (Eight Mile Plains). With more than 10 years of experience in Australian taxation and business advisory, Lily has helped over 500 small businesses, sole traders and individual taxpayers across both cities. She is a member of CPA Australia and the National Tax & Accountants' Association (NTAA), and Wiselink is a registered tax agent and ASIC-registered agent, as well as a Xero, MYOB and QuickBooks Partner. Lily works in both English and Mandarin, and writes regularly on Australian tax, EOFY planning, payroll, superannuation, SMSF and small-business strategy.

Related Posts

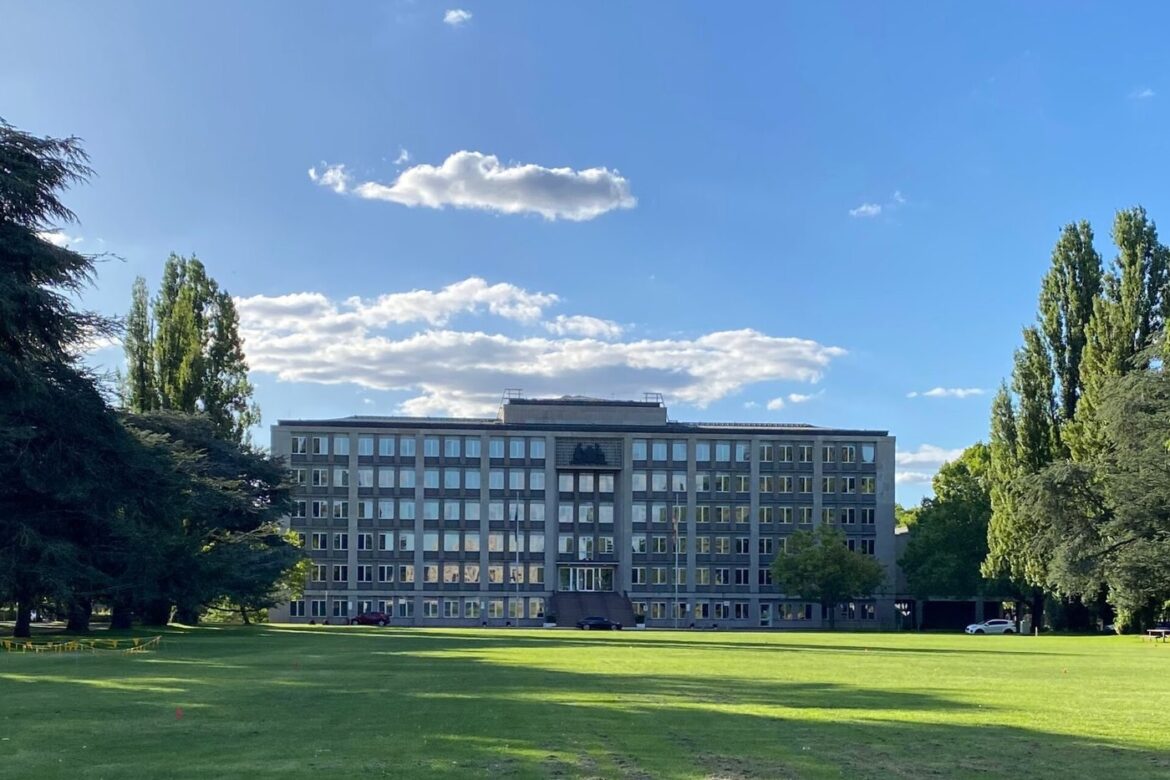
The Treasury Building in Canberra, where the exposure draft for the 30 per cent minimum tax on discretionary trusts was released on 3 September 2026

11

Sep
All Topics, Business Solutions, English Post, Finance Services

Trust Minimum Tax 2028: The Election Instead of Restructuring

Treasury released the draft legislation for the 30 per cent minimum tax on discretionary trusts on 3 September 2026, and submissions close on 18 September. The rate and the 1 July 2028 start date were already known. What is new is a third option: a trust in existence at 1 July 2028 can elect to make fixed distributions to pre-nominated beneficiaries and avoid the minimum tax, with no restructure and no stamp duty expected. One condition cancels it, and revocation costs a year at the top marginal rate plus Medicare levy.

澳大利亚高等法院 2026 年 6 月 10 日就信托未付分配权益与 Division 7A 作出判决 —— 墨尔本布里斯班华人会计

09

Sep
All Topics, Business Solutions, Chinese Post, English Post, Finance Services

信托分给公司的钱算不算借款:高等法院 6 月 10 日判了不算,但已经签成贷款协议的退不回去

每年 6 月 30 日把信托收入分一部分给自己的公司,钱没真付过去,会计说要么付掉要么签贷款协议。这句话在 2026 年 6 月 10 日之后不再成立:高等法院以 5 比 2 判税务局败诉,认定公司受益人的未付分配权益本身不是 Division 7A 的贷款,ATO 已定撤回 TD 2022/11。但已经按旧口径签成贷款协议的退不回去,本财年最低还款按 8.77% 的基准利率算;Subdivision EA 与第 100A 条也仍然适用。而财政部 9 月 3 日的信托最低税草案意见期 9 月 18 日截止,未付权益的立法将另行推进。